Nigeria’s Market Recovery Meets an Inflation Test
EXECUTIVE SUMMARY
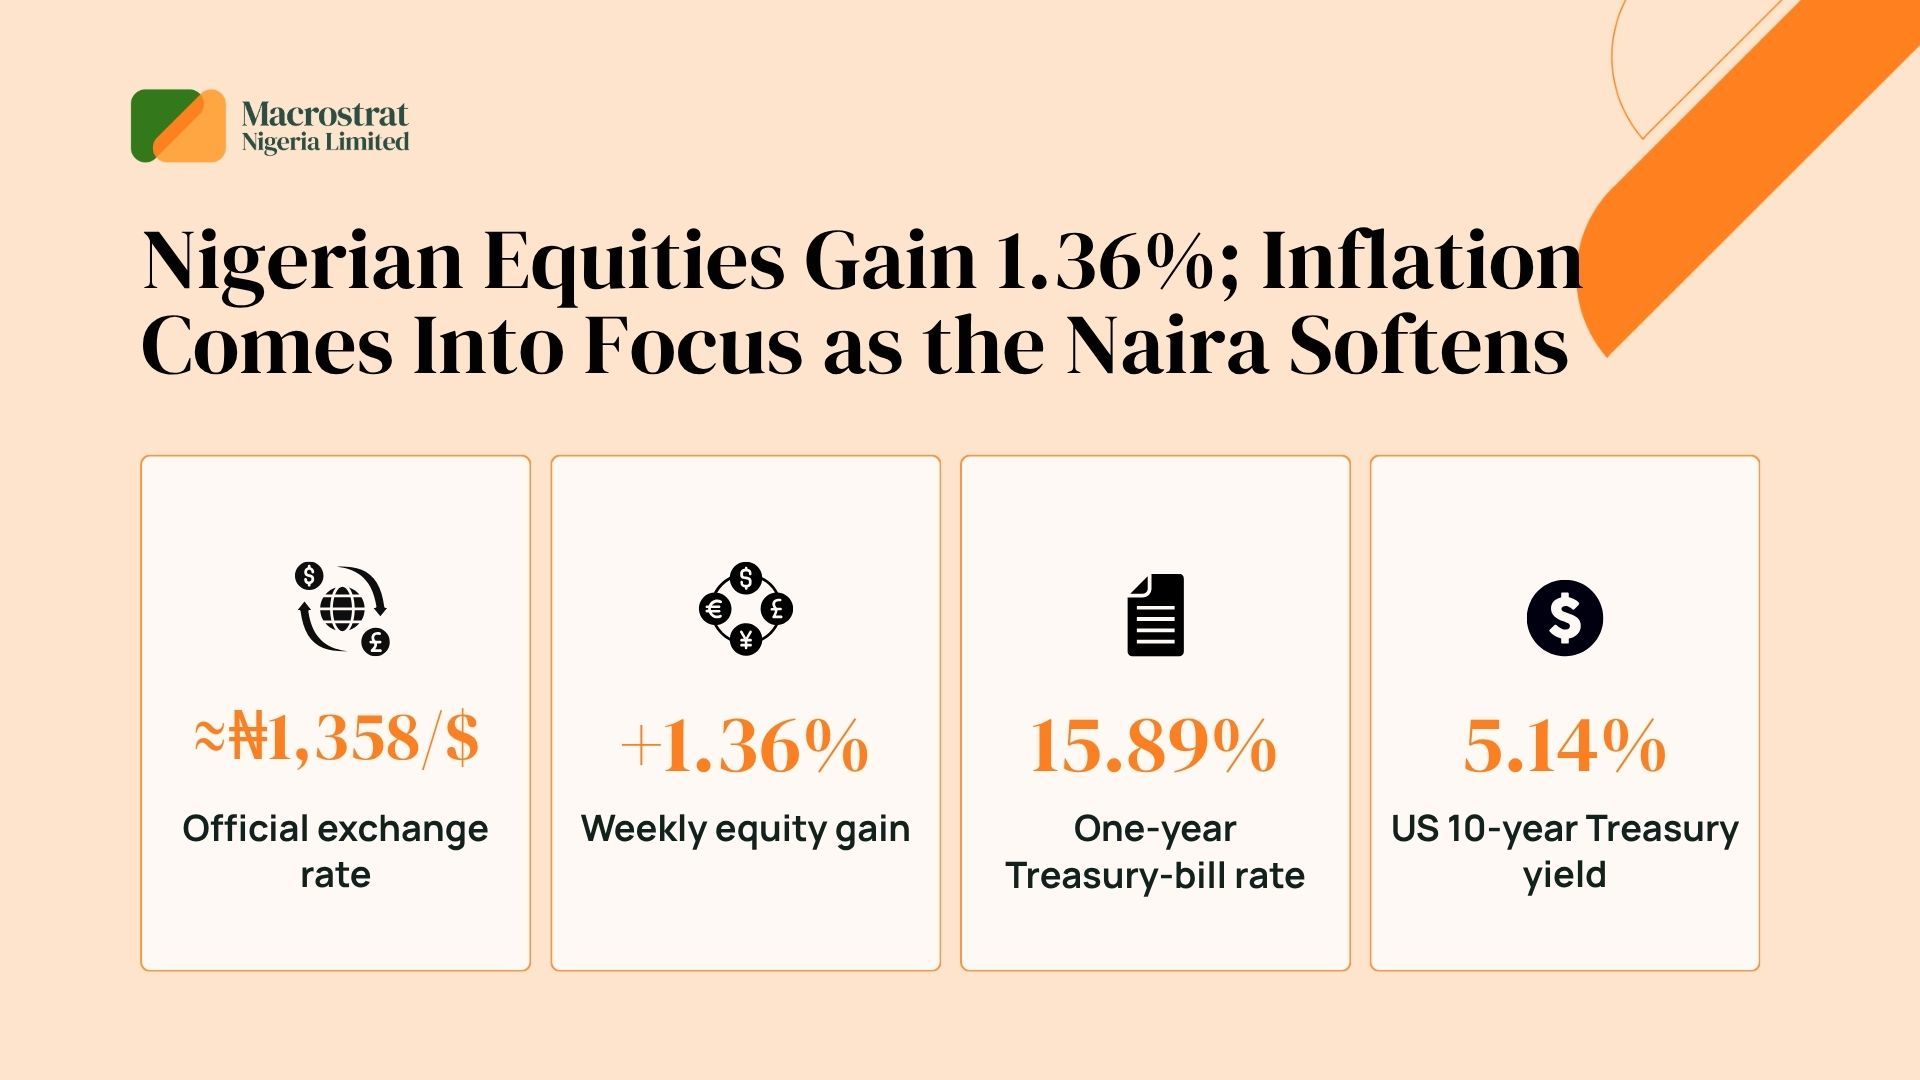
Inflation set the tone. A hot US CPI and a hawkish Fed lifted the 10-year Treasury yield to 5.14%, strengthened the dollar and kept Brent near $96, while Nvidia’s CEO resignation and the Anthropic IPO put AI at the centre of markets. In Africa, Egypt’s inflation eased to 12.7%, Uganda held at 12% and South Africa’s unemployment rose to 33.7%. In Nigeria, equities rebounded ₦2.20trn, the one-year bill cleared at 15.89% and reserves stood at $55.1bn, but the naira slipped to about ₦1,358/$. Next week: Nvidia results and Dangote’s SEC clearance (17 Nov), Anthropic’s pricing (18 Nov) and the SARB decision (19 Nov).
–
INTRODUCTION
This note reviews 8–14 Nov and previews 15–21 Nov 2026 for the world, Africa and Nigeria.
–
THE WORLD
Review. Inflation drove prices. US October CPI (10 Nov) rose 0.4% m/m against 0.3% expected, with core at 0.3% for a third month; no annual rate was published because October 2025 data were not collected during the shutdown. Fed Governor Waller said the same day that a 50bp December hike should be considered if core stays at 0.3% or more, and markets priced a hike on a 3.75–4.00% range. By the week’s close (13 Nov) the 10-year yield was 5.14%, the 30-year mortgage rate 7.50%, the dollar index above 103, and existing-home sales had fallen 5.5% to a 16-year low. AI took centre stage: on 12 Nov Nvidia announced that Jensen Huang had resigned as CEO and director, with CFO Colette Kress interim CEO, yet the Nasdaq had its best week since August; Anthropic set a $70–78 IPO range, reportedly multiple times oversubscribed, with a $26bn private placement to Alphabet, Nvidia, Microsoft and TSMC. With no other large borrowers making room in the bond market, AI-related corporate borrowing is crowding out rate-sensitive sectors. Brent ended at $96 and WTI at $89 after Washington said it needs no Iran deal; gold fell 5% and the yen touched 160. UK Q3 GDP (12 Nov) rose 0.7% q/q on AI and services, and China’s factory-gate prices rose 5.7% y/y in October.
Outlook. Nvidia reports on 17 Nov, its first results under interim leadership. US retail sales (17 Nov, +0.2% expected), housing starts and FOMC minutes (18 Nov) will test the hike path, while UK CPI (18 Nov, 3.6% expected) and Japan’s Q3 GDP (16 Nov, +0.2%) matter for the Bank of England and the yen. Anthropic prices on 18 Nov and trades on 19 Nov; flash PMIs are due around 20 Nov.
–
AFRICA
Review. Disinflation diverged from tightening. Egypt’s urban inflation slowed to 12.7% in October from 13.9% (CAPMAS, 10 Nov), yet the central bank hiked 100bp on 29 Oct, to a 20.0% deposit rate, and meets next on 17 Dec. Uganda held its policy rate at 12% on 9 Nov as inflation rose to 5.8% and is projected at 7.5–8% on energy prices and adverse weather, widening its corridor to ±3 points. South Africa’s Q3 unemployment edged up to 33.7%, about 8.6m jobless. Ghana’s 2027 Budget (12 Nov) launches a US$10bn “New Economy” programme for 2027–2030.
Outlook. The SARB decides on 19 Nov with the repo at 7.25%, and economists were split between a 25bp hike and a hold. Dollar strength from US yields is the common risk for African currencies, and the watch-points are Ghana’s post-budget detail and Egypt’s fading base effects.
–
NIGERIA
–
Review. Equities: the ASI closed at 252,269.16 on 13 Nov, up 1.36% on the week and adding ₦2.20trn to ₦163.80trn (up 64.82% year to date), led by industrials (+6.11%) and Dangote Cement (+9.61% to ₦1,469.90), after ₦3.7trn was lost on 10 Nov. Money market: at the 11 Nov auction the 364-day bill cleared at 15.89% (91-day 15.40%, 182-day 15.79%), with ₦713.31bn allotted of ₦800bn offered. FX: the official rate weakened from ₦1,349 (6 Nov) to ₦1,353.50 (10 Nov) and about ₦1,358 on 13 Nov, while the parallel market quoted ₦1,445 on 12 Nov, a gap near ₦87; gross reserves were $55.13bn on 5 Nov. Industry: NUPRC put October crude output at 1.51m bpd, down 1.7% m/m but above the 1.5m OPEC quota for a sixth month. Investment: Dangote Refinery’s ₦2.15trn IPO closed on 27 Oct and its allotment basis was due at the SEC on 10 Nov. No PMI, GDP or labour-force print fell in the window.
Outlook. The NBS is due to publish October CPI around 16 Nov, after September’s 14.63% (m/m 0.06%). SEC clearance of the Dangote allotment is targeted for 17 Nov, ahead of a provisional 8 Dec listing. The CBN, which reset its MPR to 23% on 22 Sep, meets later in November; with US yields above 5%, Macrostrat sees the rate gap raising the bar for further easing.
–
CONCLUSION The world is tightening into resilient growth: sticky US inflation, a likely December hike and 5% yields are lifting the dollar and testing emerging markets, while Nvidia’s leadership change and Anthropic’s listing keep AI at the centre. Africa splits between disinflation (Egypt) and tightening (Uganda, possibly South Africa). Nigeria enters next week with buffers (reserves above $55bn, bills near 15.9%, MPR 23%) but a softer naira and a calendar led by October CPI and the refinery allotment.
–
RECOMMENDATIONS
Policymakers: keep FX and reserve data transparent, weigh the US rate gap before further easing, and speed SEC clearance and refunds for the Dangote IPO to protect liquidity. Businesses: hedge dollar costs, plan for a wider official–parallel gap and lock funding while the one-year yield is near 15.9%.
Investors: stagger exposure around Nvidia (17 Nov), US retail sales (17 Nov) and the FOMC minutes (18 Nov), favour earnings-backed NGX names over thin small caps, and keep dollar-bond duration short while the 10-year is above 5%.